
But then the question arises: is it realistic to keep leveraging without taking these variables into account? Who benefits from this?
The concept of leverage is very beautiful and elegant, mathematically speaking, because it works perfectly when performing mathematical exercises to balance the WACC and the VAN, and because everyone can understand it, since it essentially defines a percentage weighting between two factors. But it is equally clear that its purpose is not to accurately represent reality.
And if it is reality that we are going to evaluate, then let’s reiterate: What is the point of conducting this kind of analysis?
In reality, there are other concepts for defining the correct representation and also the correct financial optimization of the project.
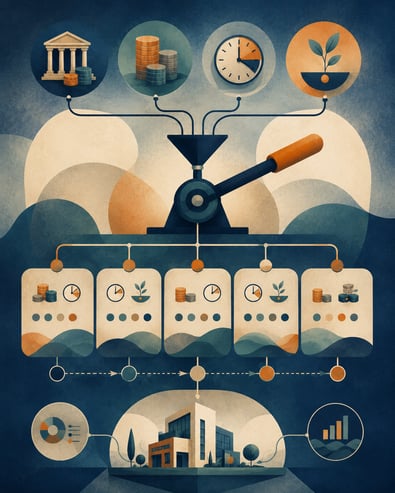 The concept of Timing, that is, the moment or period during which a financing line can be drawn upon to provide coverage. The concept of Maximum Amount, that is, the maximum amount that this line can provide. For example, how much equity can I contribute as an investor? The concept of Priority of Drawdown: which line should we draw upon first until its maximum amount is exhausted? My equity line? The equity lines of other partners we’ve already secured? The equity lines from partners I have yet to find? The bank’s debt line offering me the best rate and terms, or the bank’s debt line offering me the worst? The lines from financial partners? Self-financing of the project—that is, do I first cover the Capex with any prior positive cash flow and then save on funding sources? All of this constitutes the concept of Intervention Priorities and the added value it can provide in terms of financial savings.
The concept of the Dividend Policy: How do I distribute dividends among the partners? In relation to the equity each partner contributes? And if some partners contribute their own real estate assets, how will the dividends be redistributed? And what if some shareholders contribute their expertise—for example, they’re doctors and we’re planning to launch an innovative nursing home project? The concept of debt repayment terms: depending on my project’s cash flow, do I prefer fixed installments, a fixed principal amount, a bullet payment with or without interest capitalization, or a customized repayment schedule based on closing costs? The concept of debt repayment frequency: would I prefer a credit line offered by Bank A with annual prepayment or a credit line offered by Bank B with monthly post-payment? The concept of additional facilities: if I have a VAT facility, a working capital facility, or a series of bridge loans that I can include, how do they fit into this overall framework?
The question is: Can the added value of financial analysis be considered complete when financial leverage is taken into account, given all these variables that must be considered for a specific financial line?
The concept of Timing, that is, the moment or period during which a financing line can be drawn upon to provide coverage. The concept of Maximum Amount, that is, the maximum amount that this line can provide. For example, how much equity can I contribute as an investor? The concept of Priority of Drawdown: which line should we draw upon first until its maximum amount is exhausted? My equity line? The equity lines of other partners we’ve already secured? The equity lines from partners I have yet to find? The bank’s debt line offering me the best rate and terms, or the bank’s debt line offering me the worst? The lines from financial partners? Self-financing of the project—that is, do I first cover the Capex with any prior positive cash flow and then save on funding sources? All of this constitutes the concept of Intervention Priorities and the added value it can provide in terms of financial savings.The concept of the Dividend Policy: How do I distribute dividends among the partners? In relation to the equity each partner contributes? And if some partners contribute their own real estate assets, how will the dividends be redistributed? And what if some shareholders contribute their expertise—for example, they’re doctors and we’re planning to launch an innovative nursing home project? The concept of debt repayment terms: depending on my project’s cash flow, do I prefer fixed installments, a fixed principal amount, a bullet payment with or without interest capitalization, or a customized repayment schedule based on closing costs? The concept of debt repayment frequency: would I prefer a credit line offered by Bank A with annual prepayment or a credit line offered by Bank B with monthly post-payment? The concept of additional facilities: if I have a VAT facility, a working capital facility, or a series of bridge loans that I can include, how do they fit into this overall framework?
The question is: Can the added value of financial analysis be considered complete when financial leverage is taken into account, given all these variables that must be considered for a specific financial line?
Optimize your project's financial structure based on real-world constraints, resources, and timelines. Contact Finance Atena.

n our opinion, absolutely not. In fact, in many cases, the concept of financial leverage doesn’t even serve as the starting point for this type of analysis, because—in reality—it goes beyond that concept. And that is why, at Finance Atena, we can manage an unlimited number of equity lines, an unlimited number of debt lines, and an unlimited number of shareholder financing lines, each of which can handle all these aspects.
The definition of financial optimization, in relation to the actual financial assumptions of the Company or the Project, is what we mean by Financial Analysis.
Leverage is a result, almost never an assumption.
The definition of financial optimization, in relation to the actual financial assumptions of the Company or the Project, is what we mean by Financial Analysis.
Leverage is a result, almost never an assumption.
 Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua.
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua.
